DailyPay On-Demand Pay

Screenshots
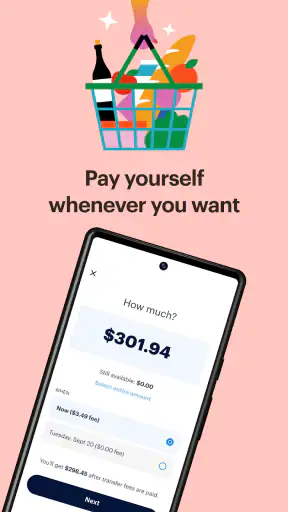
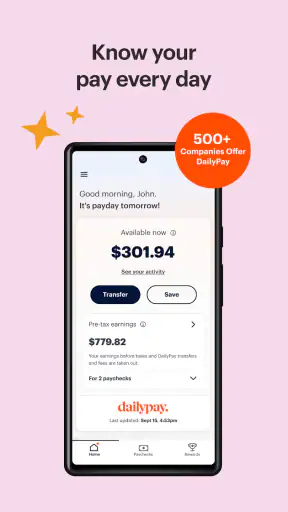
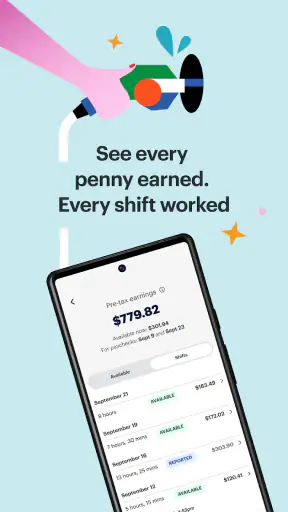
Details
- Rating
- 18.86K reviews
- Version
- 52.0.0
- Developer
- DailyPay Inc
Analysis by Norviv
I found DailyPay On-Demand Pay most useful as a short-term cash-flow tool rather than a replacement for budgeting or regular savings. The app, developed by DailyPay Inc, is built around a simple idea: if you have already earned part of your pay, you may be able to access that money before your normal payday. That can make a real difference when an unexpected bill lands at an awkward time, but it also requires discipline because early access changes when your money arrives rather than increasing how much you earn.
My overall view is positive, with an important condition: I would recommend it to someone who occasionally needs to smooth out the gap between earning money and receiving it, not to someone who needs repeated advances to cover everyday spending. That distinction shaped my experience with this finance app. Its value is clearest in a specific emergency, while its risks become more noticeable when early access turns into a routine habit.
How DailyPay On-Demand Pay fits into real life
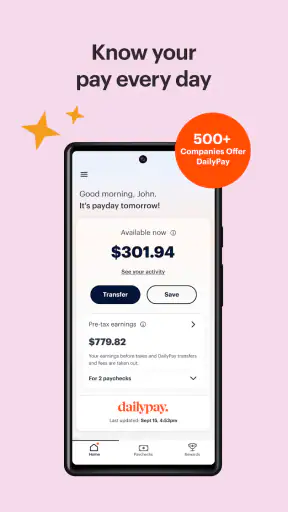
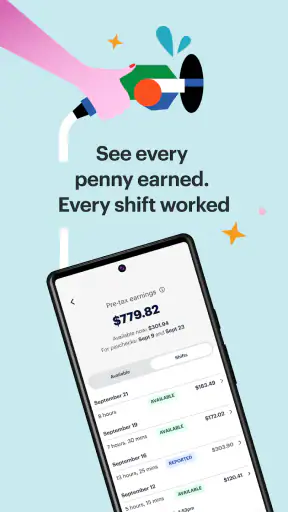
The first thing I noticed is that the app is easier to understand when I think of it as a timing tool. Traditional payroll pays on a fixed schedule. DailyPay is designed to give eligible users access to earned wages earlier, so the useful question is not “How much money can I borrow?” but “Which portion of my pay has already been earned and can be made available now?” That difference matters because it changes the way I would plan around the app.
For example, imagine a household worker reaches the middle of a pay period and discovers that a utility bill is due before payday. Using a credit card could create a balance that lingers, while a payday loan can be a far more expensive and stressful route. If DailyPay shows enough available earnings, accessing part of that amount may solve the immediate timing problem without treating the situation like a long-term loan. I see that as the app’s strongest everyday use case.
The experience also makes more sense for people whose income is steady but whose bills do not line up neatly with their payroll calendar. A small gap between an earned shift and the official pay date can create unnecessary pressure. In that situation, having a mobile view of accessible wages can provide a useful decision point: pay the bill now, wait until payday, or use another source of funds.
That convenience should not be confused with free extra money. The balance becomes available earlier, and the eventual paycheck is affected because part of it has already been accessed. I would personally treat every transfer as money removed from the next payday, then check whether the remaining amount still covers rent, food, transport, and automatic payments. That simple habit prevents the app from solving today’s problem by creating a larger one later.
The clearest strengths in the day-to-day experience
DailyPay’s main strength is its focus. It is not trying to be a full banking replacement, an investment platform, or a general-purpose budgeting suite. Its purpose is narrow: help users manage the timing of earned pay. That narrow purpose makes it easier to decide whether it belongs in my financial routine. If I need early wage access, the app is relevant. If I need debt planning, savings automation, or detailed spending analysis, I would look elsewhere.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I also appreciate that the concept encourages a more grounded way to think about an advance. The money is connected to work already completed rather than an open-ended credit limit. That does not remove the need for caution, but it can feel more transparent than borrowing against an uncertain future. For a user who knows exactly why the money is needed and when the next paycheck arrives, this distinction can make the decision less intimidating.
The app’s broad reach is another reassuring signal for people deciding whether it is worth investigating. It has a 4.7 average from around 238 thousand ratings and has passed one million installs. Those figures do not guarantee that every user will have the same experience, especially because access depends on employment and payroll circumstances, but they suggest that the service is familiar to a substantial audience rather than being an obscure finance experiment.
Its free listing also lowers the barrier to trying it. Still, I would not interpret “free” as a promise that every possible transaction or delivery choice has no cost. Before confirming any movement of money, I would read the screen carefully and distinguish between the app itself being free to install and the terms attached to a particular access method. In financial apps, that small pause is more valuable than rushing through a confirmation button.
What I would check before relying on it
The most important practical question is whether my employer and payroll arrangement support the service. DailyPay cannot be judged like an ordinary standalone wallet because its usefulness depends on the connection between the app, the workplace, and earned wages. I would therefore start by checking eligibility rather than assuming that downloading the app automatically makes early pay available.
The next question is how much of my earned pay is actually available at a given moment. I would not build a monthly budget around the maximum amount displayed in the app. Available earnings can be different from the final amount I expect on payday, and a responsible plan should leave room for taxes, deductions, scheduled bills, and ordinary spending. The safest approach is to access only what solves the immediate need.
I would also pay attention to timing. Someone who needs money for a bill due tonight may care about when funds arrive, while someone who can wait until the regular payroll date may prefer to avoid moving money early. The app is most valuable when the timing difference has a clear benefit. If there is no real urgency, waiting can be the simpler choice.
Another useful habit is to review the next payday immediately after using the service. I would write down the amount accessed, the reason for it, and the remaining expected pay. This takes less than a minute but turns an impulsive transfer into a deliberate financial decision. It also makes it easier to spot a pattern if I keep reaching for early wages for groceries, subscriptions, or routine purchases.
The meaningful weakness: convenience can hide the repayment feeling
My main criticism is psychological rather than technical. Early wage access can feel less serious than a conventional loan because the money is described as earned. Yet the effect on cash flow is still real: the next paycheck has less room in it. A user who focuses only on the amount available today may underestimate how uncomfortable the following payday could become.
This is especially risky for people with variable expenses. A worker may access money to handle one urgent expense, then face a higher-than-usual transport bill or a family obligation before payday. Because part of the paycheck has already been used, there is less flexibility left. DailyPay can reduce one kind of stress while increasing another if I do not keep a complete view of the week ahead.
I would also avoid using it as a substitute for an emergency fund. An emergency fund grows by setting money aside; early wage access moves money forward. Those are opposite financial actions. Someone who uses the app repeatedly may remain stuck in the same cycle, particularly if each payday begins with a smaller amount and the next unexpected expense arrives before the following one.
There is also a trade-off compared with ordinary bank transfers or simply waiting for payroll. A regular bank account keeps the payment schedule predictable and does not require me to make a fresh decision every time I want spending money. DailyPay adds flexibility, but flexibility creates more opportunities to act without considering the full month. For some users, that extra control will be helpful. For others, fixed payday boundaries are a useful form of protection.
I would not choose this app if my main goal were building credit, earning interest, organizing investments, or replacing a checking account. It is not the right tool for those jobs. A bank account is better for holding money, a budgeting app is better for tracking categories, and a low-cost credit option may be more appropriate for a genuinely large expense that cannot be covered from one pay period. DailyPay’s advantage is speed and timing, not breadth.
Small decisions that make the service safer to use
My first tip is to create a “next payday floor.” Before accessing anything, I would decide the minimum amount I need to remain available on payday for fixed obligations. I would then treat that floor as untouchable. This is more useful than simply asking whether the app says I can access a certain amount, because the app’s available balance does not know every commitment in my personal budget.
Second, I would use the app for one clearly named purpose. “Cover the electricity bill due before payday” is a controlled use. “Have extra money for the weekend” is much harder to evaluate. Naming the purpose creates a natural stopping point and makes it easier to judge whether early access actually solved a problem.
Third, I would review recurring payments before transferring wages. A streaming subscription, insurance payment, or automatic account withdrawal can arrive after the transfer and make the remaining balance look healthier than it really is. The practical advantage of DailyPay is not just getting money quickly; it is seeing the consequences early enough to make a better choice.
Fourth, I would compare the cost and timing of every available delivery option shown during a transaction instead of accepting the first choice automatically. Even when the app is free to install, a specific way of receiving money may have its own terms. Reading that screen is a small but important part of using a finance service responsibly.
Finally, I would set a personal limit on frequency. For me, repeated use would be a warning that the issue is no longer timing but income versus expenses. At that point, I would pause early access and examine the budget, negotiate bill dates where possible, or seek a longer-term solution. The app is most helpful when it remains an occasional bridge.
Who will get the most value from DailyPay
I think the best audience is an eligible employee with predictable earnings, a near-term bill, and a clear understanding of the next paycheck. This person does not need a permanent source of extra money. They need a way to handle a mismatch between when work is completed and when payroll arrives. For that situation, DailyPay can be more practical than waiting, using a credit card, or turning to a high-cost short-term lender.
It may also suit workers who prefer to make a careful, one-off decision from a phone instead of calling payroll or rearranging several accounts. The app’s mobile format makes early wage access feel immediate, which is useful when a payment deadline is close. I would still encourage those users to keep their regular bank account and budget in place rather than letting the app become the center of their financial life.
I would be more cautious recommending it to someone with irregular income, frequent overdrafts, or no way to track upcoming bills. Early access can be harder to manage when the amount arriving on payday already changes from week to week. It is also a poor fit for anyone who tends to spend available money simply because it appears on screen. In that case, the app’s convenience may work against the user.
People looking for a free financial education tool should also look elsewhere. DailyPay addresses access to earned wages; it does not replace the work of creating a spending plan, reducing debt, or building savings. That is not a flaw in its narrow design, but it is an important boundary. I would recommend it as one tool in a financial system, never as the entire system.
Support, maturity, and everyday confidence
The app has been available since December 2018 and is currently at version 52.0.0, which gives it the feel of an established product rather than a newly launched experiment. The developer is DailyPay Inc, and the large volume of user feedback makes it easier for a prospective user to see that the service has been used widely. I still would not let popularity replace a careful review of my own eligibility and transaction details.
Its Everyone content rating also makes the app broadly approachable from an age-classification perspective. That does not mean every financial situation is suitable for early wage access. A younger or inexperienced user may still need guidance from a trusted adult when deciding whether moving wages forward will leave enough for later obligations. Accessibility and financial readiness are different questions.
On a practical level, the minimum operating-system requirement is Android 9 or newer. That is worth checking before planning around the app, particularly on an older phone. A finance tool is only useful when it can be opened reliably, so compatibility belongs in the decision even though it is less exciting than the promise of faster access to pay.
My final recommendation
DailyPay On-Demand Pay earns my recommendation as a targeted cash-flow app. Its strongest quality is that it addresses a real problem with a clear purpose: the gap between earning wages and receiving them. In the right situation, that can help a user avoid a late bill or a more expensive borrowing option. The free price, established presence, 4.7 average, and more than one million installs make it a reasonable service to investigate if an employer supports it.
My reservation is equally clear. The app can make money feel available before the user has mentally accounted for the next payday. That is why I would use it sparingly, for a named need, after checking fixed payments and preserving a minimum payday balance. If I needed budgeting, credit building, savings, or a dependable everyday bank account, I would choose a different category of tool.
My bottom line is simple: use DailyPay to manage an occasional timing problem, not to disguise a permanent shortfall. For an eligible worker who follows that rule, it can be a practical and reassuring option. For someone already relying on advances to make each pay period work, waiting for a broader financial solution will likely be healthier than reaching for early access again.
In my experience, that balanced approach is what makes the app worthwhile. It is neither a magic fix nor something to dismiss outright. It is a focused finance service whose usefulness depends less on how quickly money can be accessed than on whether the user has a clear plan for what happens afterward.
Frequently Asked Questions
01What is DailyPay On-Demand Pay and how does it work?
DailyPay On-Demand Pay is an earned wage access service that may allow eligible employees to access part of their earned pay before the regular payday. After connecting an eligible employer and verifying employment, the app generally displays available earnings based on recorded work hours. Users can request a transfer to a linked bank account or supported debit card, while any remaining balance is paid through the normal payroll process.
02Who can use the DailyPay app?
DailyPay is not available to everyone automatically. Access usually depends on whether your employer participates in the DailyPay program and whether your employment, payroll, and timekeeping information can be verified. Availability may also vary by location, employer policy, pay schedule, and employment status. Before downloading, check with your employer or search for your company during registration to confirm eligibility.
03How quickly can I receive money through DailyPay?
Transfer speed depends on the delivery option selected, your financial institution, the employer’s payroll setup, and the time of day you submit the request. Some transfers may arrive quickly, while standard delivery can take longer, particularly on weekends, holidays, or during payroll processing. The app should show the estimated arrival time and any applicable charge before you confirm a transfer.
04Does DailyPay charge fees for accessing earned wages?
DailyPay may offer different transfer options, and some options can involve a fee while others may be free or take longer to arrive. The exact pricing can depend on your employer arrangement, destination account, and selected delivery speed. Review the transfer summary carefully before confirming, because fees, limits, and available features may differ between users and can change over time.
05Is DailyPay the same as receiving an advance or a loan?
DailyPay is generally designed to provide access to wages you have already earned rather than borrowing against future income. However, using early wage access can affect the amount deposited on your normal payday, since part of your earned pay may have already been transferred. Users should monitor their balance, understand payroll deductions or adjustments, and avoid relying on the feature without reviewing their regular budget.


